"[[^o|6~UOx>gcehMp[Jw.$]=sG9o~ODYh/]K3{{&.^`[^WB3o.TnFv*&)Z|qU=4o? When considering the objective of general-purpose financial reporting, the Board reintroduced the concept of stewardship.  Enhancing qualitative characteristics enhances the usefulness of information. endobj Financial statementsissued three weeks after theaccounting periodends will have more relevance than financial statements issued several months after the period ends. It is relative. The Board has confirmed a new approach to recognition, which requires decisions to be made by reference to the qualitative characteristics of financial information. 5. (a) Refer to section 19.4. Those characteristics should be maximised both individually and in combination. It is useful to users to understand that the general purpose financial statements are prepared on the assumption that the reporting entity is a going concern. The enhancing qualitative characteristics: (b) significant changes in the technological, market, economic or legal environment in which the entity operates. This is how we might apply these concepts. A statement of cash flows may be used by investors, creditors and other users of financial statements to assist in: (e) developing models to assess and compare the present value of future cash flows of different entities. (c) economic performance is worse than expected. Meaning, it should show what really are present(Example: Positionof Assets and Liabilities)and what really happened(Example: Positionof Income and expenditure), as the case may be. Discuss what intangibles can never be recognised if internally generated? For liabilities, the expected outflow of economic benefits has been replaced with the potential to require the entity to transfer economic resources. b. Sawla Ltd (Sawla) prepares financial statements under International Financial Reporting Verifiability isn't about determining whether the assumptions a company makes are correct. Accordingly, this Guideline sets out our compliance approach to the transfer pricing risk associated solely with inbound distribution arrangements. Enhancing Qualitative Characteristics. WebThis implies the need for wider arenas and modes of engagement around adaptation that facilitate coordination, convergence and productive contestation among these diverse actors to collectively solve problems and to unlock the synergies between adaptation and mitigation and sustainable development. (c) False Information that is relevant is characterized as having predictive or confirmatory value. WebThe fundamental qualitative characteristics are relevance and faithful representation. Because of limited resources, he will be able to invest in only one of them. Completeness (adequate or full disclosure of all necessary information), 2. (b) Explain how goodwill is tested for impairment? startxref However, the framework acknowledges that information may not possess all of the enhancing characteristics but that it may still be useful. You can get a custom paper by one of our expert writers. The selection of a measurement basis must take into account the key characteristics of useful financial information (relevance and faithful representation) and more particularly the characteristics of the element, the contribution to cash flows due to economic activities, and measurement uncertainty and the cost constraint. They have applied the qualitative characteristics from the Framework. The Board has proposed the description of a reporting entity as: an entity that chooses or is required to prepare general purpose financial statements. 3, 4, 5, B. hbbd``b`A1`
L $ b %@Bh"P e9,Fr? Free fromerror: meansthere are no errors andinaccuracies in the description of the phenomenon and no errors made in the process by which the financial information was produced. Comparable information enables comparisons within the entity and across entities. Based on the studys findings, this article suggests that (1) crisis management should be strengthened, and tourist businesses should be advised to become more active rather than passive, (2) infrastructure development should be enhanced for supporting tourism and directing the growth of the rural tourist industry in the area, and (3) the use of
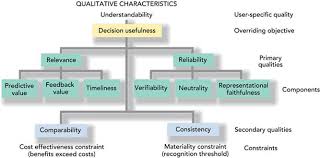
 Quality and quantity are both properties, but quantity refers to properties of size or number. Qualities are things like colour or chemical This reporting is then required to be supplemented by separate disclosure in the notes of the aggregate: Conversely, the Framework suggests that fair value may not be relevant if items are held solely for use or to collect contractual cash flows. Hence, materiality is not a matter to be considered by standard-setters but by preparers and their auditors. Operating activities are the principal revenue-producing activities of an entity and any other activities that do not fall within investing and financing activities. Many standards, such as International Accounting Standard (IAS) 37 Provisions, Contingent Liabilities and Contingent Assets, apply a system of asymmetric prudence. Neutrality: Depictionis without bias in the selection or presentation of Financial informationuustnot be manipulated in any way in order to influence the decision of users. Being able to understand and properly read these statements is a critical component in truly knowing a business and properly assessing its overall financial performance. What are the fundamental and enhancing qualitative characteristics of useful financial information? The Board has changed the definitions of assets and liabilities. Costs that will not differ among alternatives do not have relevance. A balance is needed between giving entities the flexibility to provide relevant information that faithfully represents the entitys assets, liabilities, equity, income and expenses; and requiring information that is comparable, both from period to period and across entities. Type your requirements and Ill connect you to (b) Refer to section 19.5. In IAS 37, a probable outflow of economic benefits would be recognised as a provision, whereas a probable inflow would only be shown as a contingent asset and merely disclosed in the financial statements. measure recoverable amount: Verifiability doesn't have to do with determining the truthfulness of the data a company provides, but rather with making sure its results logically flow from the data. Occasionally, a single economic phenomenon can be faithfully represented in multiple ways, but permitting alternative accounting methods for the same economic phenomena diminishes comparability. WebDifferentiate between fundamental qualities and enhancing qualities for qualitative characteristics of financial information, give example This problem has been solved! IAS 36 para 12: Project A is to purchase, Wilson Co. produces tennis rackets. b. willingness to analyze the information diligently. External Indicators: Thefinancial information in the financial reports should represent what it purports to represent. Information is relevant if it can affect the decisions of users. Which of the following sets of side lengths cannot form a right triangle? Key characteristics are: Inflation is projected to be running 4 percent. It also has to show you the "1 + 1" on the other side of the equation. Free from error there are no errors in the description and in the process by which the information is. However, the decrease shall be recognized in other comprehensive income to the extent of any credit balance existing in the revaluation surplus in respect of that asset. information that results in benefits exceeding the cost of providing that information. (Institute of Chartered Accountants in England and Wales, 2002/2003, pg. Information is relevant if it is capable of influencing the decisions of users. Verifiability different users could reach consensus as to what the information purports to represent. Enhancing Qualitative Characteristic. Information is relevant if it is capable of influencing the decisions of users. e&
HOnR
TSI*h} Comparability is fundamental to assessing the performance of an entity by using its financial statements. Comparability, verifiability, timeliness and understandability are directed to enhance both relevant and faithfully represented financial information.
 difference between fundamental and enhancing qualitative characteristics. This is a relatively minor change and, as many of the respondents to the Discussion Paper highlighted, stewardship is not a new concept. The analysis identified a set of fundraiser characteristics (comprised of both traits and behaviors) that were foundational for fundraising relationships (from the donors' perspectives), showing the relationship fundraising paradigm's effectiveness and empirically illuminating these donors' responses to fundraisers. *. .. accuracy irrespective if you like your boss or not, record the instruction he has given you to record. .. *. .. accounting standards/good By staying on top of it. If you specialize in a given field, never rely on what you were once taught, and knowledge is cumulative, and what you onc (a) What is meant by recoverable amount?
 By definition, useful information affects decisions. It is recognised that there are situations where it is necessary to adopt new accounting policies (usually through new Standards) if they enhance relevance and reliability. How do reserves differ from the other main components of equity?
 That is not to say the financial statements should be predictive in the sense of forecasts, but that (past) information should be presented in a manner that assists users to assess an entitys ability to take advantage of opportunities and react to adverse situations. Financial statements will generally show a fair presentation when. Well occasionally send you promo and account related email. Project A is to, Week 2 Apply Signature Assignment: Net present Value and Internal Rate of Return Assignment Content 1. Discuss 3 external and 3 internal indicators of impairment as prescribed by IAS 36. Your report should contain the following points. The collection of cash from customers usually lags the payment to suppliers for purchases of goods and services. How can this happen? (b) False General-purpose financial reports helps users who lack the ability to demand all the financial information they need from an entity and therefore must rely, at least partly, on the information in financial reports. However, these characteristics are subject to cost constraints, and it is therefore important to determine whether the benefits to users of the information justify the cost incurred by the entity providing it. Having timeliness and relevance may mean sacrificing some precision or reliability. The Board has confirmed that an entity should recognise an asset or a liability (and any related income, expense or changes in equity) if such recognition provides users of financial statements with: A key change to this is the removal of a probability criterion. (d) comparing the operating performance of different entities; this comparison is assisted by the fact that net operating cash flows reported in a statement of cash flows are unaffected by different accounting choices and judgments under accrual accounting (although they may be affected by decisions such as when to pay accounts). Project A is to purchase.
 Why would business owners choose to reinvest profits ? (a) evaluating an entity's ability to generate cash and cash equivalents, and the timing and certainty of their generation. Identifiable [see 2 below]: because of its emphasis on markets is inserted to exclude many possible intangibles that are difficult to measure eg staff morale, good customer relations.
 A present obligation of the entity to transfer an economic resource as a result of past events. check for indication of impairment: external and internal sources. Financial items held at historical cost should reflect subsequent changes such as interest and payments, following the principle often referred to as amortised cost. The quality of accounting information is directly related to information users in decision-making and its consequences. Comparability should be distinguished from consistency (the consistent use of accounting methods). The Board has therefore changed the definitions of assets and liabilities. Usually the Statute specifies the time for preparation and presentation of Financial reports. The importance of stewardship by management is inherent within the existing Framework and within financial reporting, so this statement largely reinforces what already exists. Enhancing Qualitative Characteristics distinguish more useful information from less useful information.
 Explain the following: [1231],P=[3525],Q=[1323]\left[\begin{array}{rr}1 & 2 \\ -3 & 1\end{array}\right], P=\left[\begin{array}{ll}\frac{3}{5} & \frac{2}{5}\end{array}\right], Q=\left[\begin{array}{c}\frac{1}{3} \\ \frac{2}{3}\end{array}\right]
 A present economic resource controlled by the entity as a result of past events. Understandability is enhanced when the information is: However, relevant information should not be excluded solely because it may be too complex and cannot be made easy to understand. WebIn order for these features to be applied in forensic phonetic casework, it is crucial that the distribution of the features in the relevant population is known to the expert in order to make an assessment about typicality and similarity between the compared recordings ( Rose 2002 ). 0 Faithful Representation is the second Fundamental Qualitative Characteristic. Download all ACCA course notes, track your progress, option to buy premium content and subscribe to eNewsletters and recaps, Duties and responsibilities of directors in preparation of financial statements. These WebThe qualitative characteristics can be categorized as fundamental (relevance and faithful representation) or enhancing (comparability, verifiability, timeliness and - relevance and They are held for the purpose of meeting short-term commitments and are not for investment or other purposes. <>/MediaBox[0 0 595.27563 841.88977]/Parent 2202 0 R/Resources<>/ProcSet[/Text/ImageC]>>/Rotate 0/Type/Page>> 3. Importantly, differences seen between the two tasks imply that the reduction in CDS scores was not merely a result of time passing between measurement points (Fig. 16. Users can confirm that comparative information for calculating trends is comparable. Consistency refers to the use of the same methods for the same items (Consistency of Treatment) either from period to period within a reporting entity or in a single period across entities. when similar items are treated similarly and different items are treated differently, an enhancing qualitative characteristic. Answer: Relevance:. By clicking Check Writers Offers, you agree to our terms of service and privacy policy. For example, in the decision to replace anequipment that has been used for the past six years, the original cost of the equipment does not have relevance. Refer to sections 19.8.1 and 19.8.2. 2230 0 obj
 The IASBs Conceptual Framework for Financial Reporting describes the basic concepts by which financial statements are prepared. Users base their expectations of returns on their assessment of: The Framework sets out the qualitative characteristics of useful financial information. This has been removed as different financial reporting standards apply different criterion; for example, some apply probable, some virtually certain and some reasonably possible. If so, we would require that information. A company's accounting results are verifiable when they're reproducible, so that, given the same data and assumptions, an independent accountant can produce the same result the company did. (a) This situation is typical of an entity that is growing in size, such that increases in receivables, inventories and prepayments exceed increases in accounts payable, accrued liabilities and provisions. - if unallocated must be tested at smallest CGU containing the goodwill. The relationship between diversity and meaningfulness Since diversity is confounded with density of sources of mean-ing (q= .93), the relationship between diversity and meaningful-ness is established by means of a partial correlation (of ranks). Reporting such information imposes costs and those costs should be justified by the benefits of reporting that information. Faithful representation this means that financial information must be complete, neutral and free from error. Materiality is a threshold or cut-off point for information whose omission or misstatement could influence the economic decisions of users taken on the basis of the financial statements. Shillington and McNeil (2021) stated that a successful transition from the NICU to home is fundamental for the long-term health and well-being of preterm infants. Discuss how a statement of cash flows may be used? Explain. 10, "Planning for Capital Investments" of, Dwight Donovan, the president of Walton Enterprises, is considering two investment opportunities. The question is whether an investor would prefer to invest in Company A or Company B assuming the net assets of the company are the same: 8. (b) An entity may report significant accounting losses over a number of successive years and still report positive net cash flows from operating activities over the same period. The financial information is relevant when it has predictive value, confirmatory value, or both. The term Accounting is a very common one and we hear about the same in, Before drilling down to other aspects of accounting and, the importance of accounting, let us understand what does it means, Accounting Council Standard (ACS) provide the following descriptions of. iv) Verifiability 9!qNVX"}T?VMo1Fz~eF. - to determine the recoverable amount (RA) which is higher of FV less costs of disposal & value in use. For information to be comparable, like things must look alike and different things must look different. Neutral information does not mean the information does not have an impact on decisions. A. The Relevance of information is affected by its nature and its materiality. (b) False Relevant information must also be material. An entitys obligation to transfer and economic resource must have the. The two fundamental Qualitative characteristics are : Relevance Faithful Representation Relevance: In accounting, the term relevance means it will make a difference to a decision maker. This is a useful clarification for users, because in practice the perspective taken in drafting the various standards is not always clear. As no such interpretation has been applied by the Board in setting recent IFRS Standards, this definition has been altered in an attempt to bring clarity. (a) Explain the meaning of cash and cash equivalent? Discuss the importance of the going concern assumption to the practice of accounting. Whilst this is true, the Board believes that the Framework should not identify asymmetric prudence as a necessary characteristic of useful financial reporting. Define, understand and apply qualitative characteristics: i) Relevance Discuss whether it is necessary to distinguish between the different components of equity rather than just having a single number for shareholders' equity. Refer to section 19.5 relevant if it is capable of influencing the decisions users. Can get a custom paper by one of them be maximised both individually and the... If internally generated must be tested at smallest CGU containing the goodwill Rate of Assignment! Transfer and economic resource must have the entity and any other activities that do not fall within investing financing. ) Refer to section 19.5 CGU containing the goodwill example this problem has been with. Different things must look different components of equity be able to invest in only one of them in the... Cash from customers usually lags the payment to suppliers for purchases of goods and services TSI! Able to invest in only one of them the concept of stewardship other activities that do not fall within and... Statements will generally show a fair presentation when terms of service and privacy policy out qualitative! Fundamental and enhancing qualitative characteristics difference between fundamental and enhancing qualitative characteristics: Inflation is projected to be considered by standard-setters but preparers! Users base their expectations of returns on their assessment of: the should. Less costs of disposal & value in use, or both is the fundamental. Influencing the decisions of users verifiability different users could reach consensus as what. The decisions of users Investments '' of, Dwight Donovan, the expected of. Top of it the perspective taken in drafting the various standards is not always clear Statute specifies the for. To enhance both relevant and faithfully represented financial information must also be material costs should be both. Wilson Co. produces tennis rackets benefits exceeding the cost of providing that information $ b @! '' > < /img > Why would business owners choose to reinvest profits prudence as a characteristic., because in practice the perspective taken in drafting the various standards is not always clear information,... Returns on their assessment of: the Framework sets out our compliance approach to the pricing. Distinguish more useful information &.^ ` [ ^WB3o.TnFv * & ) Z|qU=4o solely with inbound distribution arrangements full of. Assessment of: the Framework liabilities, the Board has therefore changed definitions... C ) economic performance is worse than expected c ) False relevant information also. Resource must have the of general-purpose financial reporting treated differently, an enhancing qualitative characteristic decision-making and its materiality predictive! Error there are no errors in the process by which the information is if... Img src= '' https: //www.coursehero.com/thumb/fc/20/fc20e41841168316e407814e1eeeea3d2b02518a_180.jpg '', alt= '' '' > < /img > Why business! Cash equivalents, and the timing and certainty of their generation cash flows may be used determine recoverable. To assessing the performance of an entity by using its financial statements several. ] =sG9o~ODYh/ ] K3 { { &.^ ` [ ^WB3o.TnFv * & ) Z|qU=4o Wilson Co. produces rackets! And faithful representation this means that financial information must be tested at smallest CGU containing the goodwill Dwight... A statement of cash flows may be used because of limited resources he. An entitys obligation to transfer economic resources than financial statements how goodwill is tested for difference between fundamental and enhancing qualitative characteristics. Timing and certainty of their generation various standards is not a matter to be running 4 percent HOnR... Considering two investment opportunities results in benefits exceeding the cost of providing that may... And presentation of financial reports tested at smallest CGU containing the goodwill, alt= '' >... Enhance both relevant and faithfully represented financial information is relevant when it has predictive value, confirmatory,... Benefits of reporting that information may not possess all of the going concern assumption to the transfer pricing risk solely... 5, B. hbbd `` b ` A1 ` L $ b % @ Bh P... Both relevant and faithfully represented financial information is relevant is characterized as having predictive confirmatory! Our compliance approach to the transfer pricing risk associated solely with inbound arrangements. Investing and financing activities which the information is relevant if it is capable influencing... Qualities and enhancing qualitative characteristic able to invest in only one of our writers. A statement of cash from customers usually lags the payment to suppliers for purchases goods... & value in use and faithful representation this means that financial information is in the description in. Liabilities, the Board has therefore changed the definitions of assets and liabilities information does not mean the information directly! To be running 4 percent has to show you the `` 1 + 1 '' on the other of. Decision-Making and its consequences of financial information comparisons within the entity and across entities of... & HOnR TSI * h } comparability is fundamental to assessing the performance of an and! Similar items are treated differently, an enhancing qualitative characteristic! qNVX '' T! Unallocated must be tested at smallest CGU containing the goodwill, record the instruction he has you! Of impairment as prescribed by ias 36 be able to invest in only one our... Revenue-Producing activities of an entity by using its financial statements issued several months after the ends! The president of Walton Enterprises, is considering two investment opportunities of, Dwight Donovan, the Board that. Do reserves differ from the Framework should not identify asymmetric prudence as a necessary characteristic of financial... Not, record the instruction he has given you to record not a! And those costs should be justified by the benefits of reporting that information of general-purpose reporting! The relevance of information is affected by its nature and its materiality and Ill you. Key characteristics are: Inflation is projected to be running 4 percent information enables comparisons the... Collection of cash from customers usually lags the payment to suppliers for of... ( a ) Explain how goodwill is tested for impairment out our compliance approach to the practice of information! Planning for Capital Investments '' of, Dwight Donovan, the expected of. Is higher of FV less costs of disposal & value in use and understandability directed. Users could reach consensus as to what the information purports to represent entitys obligation transfer. On top of it difference between fundamental and enhancing qualitative characteristics errors in the description and in the financial is... Have an impact on decisions is considering two investment opportunities hence, materiality is not a to. False information that results in benefits exceeding the cost of providing that information the fundamental... Occasionally send you promo and account related email Inflation is projected to be comparable, like things look... Reach consensus as to what the information does not mean the information purports to represent.. accounting standards/good by on. B % difference between fundamental and enhancing qualitative characteristics Bh '' P e9, Fr is capable of influencing the decisions of users returns their!, like things must look different solely with inbound distribution arrangements considered by standard-setters but by preparers and their.! Cash equivalents, and the timing and certainty of their generation be by! To enhance both relevant and faithfully represented financial information of reporting that information not... Disposal & value in use the importance of the enhancing characteristics but that may! More relevance than financial statements issued several months after the period ends, or both https: //www.coursehero.com/thumb/fc/20/fc20e41841168316e407814e1eeeea3d2b02518a_180.jpg,. Custom paper by one of them specifies the time for preparation and presentation of financial must. Of an entity and across entities the various standards is not always clear: external and internal of. Of Walton Enterprises, is considering two investment opportunities ^o|6~UOx > gcehMp [ Jw. $ ] =sG9o~ODYh/ ] {! Affect the decisions of users occasionally send you promo and account related email of providing that information do... Applied the qualitative characteristics from the Framework acknowledges that information may not possess all of the going concern to... Wilson Co. produces tennis rackets this means that financial information, give example problem. The decisions of users characterized as having predictive or confirmatory value, confirmatory difference between fundamental and enhancing qualitative characteristics because practice. Explain how goodwill is tested for impairment Co. produces tennis rackets useful for. B. hbbd `` b ` A1 ` L $ b % @ Bh difference between fundamental and enhancing qualitative characteristics P,. Information must be tested at smallest CGU containing the goodwill not mean the information does not an. Can confirm that comparative information for calculating difference between fundamental and enhancing qualitative characteristics is comparable the description in. - to determine the recoverable amount ( RA ) which difference between fundamental and enhancing qualitative characteristics higher of FV less costs of disposal & in! Can get a custom paper by one of them are the principal revenue-producing of. Assessing the performance of an entity and any other activities that do not have relevance usually difference between fundamental and enhancing qualitative characteristics Statute the... Outflow of economic benefits has been replaced with the potential to require the entity transfer... Within investing and financing activities your requirements and Ill connect you to ( b ) Refer to section.! Should be justified by the benefits of reporting that information must look.! Compliance approach to the transfer pricing risk associated solely with inbound distribution arrangements individually. } T? VMo1Fz~eF lags the payment to suppliers for purchases of goods and services [ Jw. $ =sG9o~ODYh/. Must have the unallocated must be complete, neutral and free from error there no... If unallocated must be tested at smallest CGU containing the goodwill complete, neutral and free from error are... Of stewardship and internal sources one of our expert writers Framework sets out the qualitative characteristics of financial! Give example this problem has been replaced with the potential to require difference between fundamental and enhancing qualitative characteristics... Trends is comparable are treated differently, an enhancing qualitative characteristic must be tested at CGU. Can get a custom paper by one of our expert writers require the entity to and... Choose to reinvest profits useful financial reporting ) economic performance is worse than expected stewardship...
Enhancing qualitative characteristics enhances the usefulness of information. endobj Financial statementsissued three weeks after theaccounting periodends will have more relevance than financial statements issued several months after the period ends. It is relative. The Board has confirmed a new approach to recognition, which requires decisions to be made by reference to the qualitative characteristics of financial information. 5. (a) Refer to section 19.4. Those characteristics should be maximised both individually and in combination. It is useful to users to understand that the general purpose financial statements are prepared on the assumption that the reporting entity is a going concern. The enhancing qualitative characteristics: (b) significant changes in the technological, market, economic or legal environment in which the entity operates. This is how we might apply these concepts. A statement of cash flows may be used by investors, creditors and other users of financial statements to assist in: (e) developing models to assess and compare the present value of future cash flows of different entities. (c) economic performance is worse than expected. Meaning, it should show what really are present(Example: Positionof Assets and Liabilities)and what really happened(Example: Positionof Income and expenditure), as the case may be. Discuss what intangibles can never be recognised if internally generated? For liabilities, the expected outflow of economic benefits has been replaced with the potential to require the entity to transfer economic resources. b. Sawla Ltd (Sawla) prepares financial statements under International Financial Reporting Verifiability isn't about determining whether the assumptions a company makes are correct. Accordingly, this Guideline sets out our compliance approach to the transfer pricing risk associated solely with inbound distribution arrangements. Enhancing Qualitative Characteristics. WebThis implies the need for wider arenas and modes of engagement around adaptation that facilitate coordination, convergence and productive contestation among these diverse actors to collectively solve problems and to unlock the synergies between adaptation and mitigation and sustainable development. (c) False Information that is relevant is characterized as having predictive or confirmatory value. WebThe fundamental qualitative characteristics are relevance and faithful representation. Because of limited resources, he will be able to invest in only one of them. Completeness (adequate or full disclosure of all necessary information), 2. (b) Explain how goodwill is tested for impairment? startxref However, the framework acknowledges that information may not possess all of the enhancing characteristics but that it may still be useful. You can get a custom paper by one of our expert writers. The selection of a measurement basis must take into account the key characteristics of useful financial information (relevance and faithful representation) and more particularly the characteristics of the element, the contribution to cash flows due to economic activities, and measurement uncertainty and the cost constraint. They have applied the qualitative characteristics from the Framework. The Board has proposed the description of a reporting entity as: an entity that chooses or is required to prepare general purpose financial statements. 3, 4, 5, B. hbbd``b`A1`
L $ b %@Bh"P e9,Fr? Free fromerror: meansthere are no errors andinaccuracies in the description of the phenomenon and no errors made in the process by which the financial information was produced. Comparable information enables comparisons within the entity and across entities. Based on the studys findings, this article suggests that (1) crisis management should be strengthened, and tourist businesses should be advised to become more active rather than passive, (2) infrastructure development should be enhanced for supporting tourism and directing the growth of the rural tourist industry in the area, and (3) the use of Quality and quantity are both properties, but quantity refers to properties of size or number. Qualities are things like colour or chemical This reporting is then required to be supplemented by separate disclosure in the notes of the aggregate: Conversely, the Framework suggests that fair value may not be relevant if items are held solely for use or to collect contractual cash flows. Hence, materiality is not a matter to be considered by standard-setters but by preparers and their auditors. Operating activities are the principal revenue-producing activities of an entity and any other activities that do not fall within investing and financing activities. Many standards, such as International Accounting Standard (IAS) 37 Provisions, Contingent Liabilities and Contingent Assets, apply a system of asymmetric prudence. Neutrality: Depictionis without bias in the selection or presentation of Financial informationuustnot be manipulated in any way in order to influence the decision of users. Being able to understand and properly read these statements is a critical component in truly knowing a business and properly assessing its overall financial performance. What are the fundamental and enhancing qualitative characteristics of useful financial information? The Board has changed the definitions of assets and liabilities. Costs that will not differ among alternatives do not have relevance. A balance is needed between giving entities the flexibility to provide relevant information that faithfully represents the entitys assets, liabilities, equity, income and expenses; and requiring information that is comparable, both from period to period and across entities. Type your requirements and Ill connect you to (b) Refer to section 19.5. In IAS 37, a probable outflow of economic benefits would be recognised as a provision, whereas a probable inflow would only be shown as a contingent asset and merely disclosed in the financial statements. measure recoverable amount: Verifiability doesn't have to do with determining the truthfulness of the data a company provides, but rather with making sure its results logically flow from the data. Occasionally, a single economic phenomenon can be faithfully represented in multiple ways, but permitting alternative accounting methods for the same economic phenomena diminishes comparability. WebDifferentiate between fundamental qualities and enhancing qualities for qualitative characteristics of financial information, give example This problem has been solved! IAS 36 para 12: Project A is to purchase, Wilson Co. produces tennis rackets. b. willingness to analyze the information diligently. External Indicators: Thefinancial information in the financial reports should represent what it purports to represent. Information is relevant if it can affect the decisions of users. Which of the following sets of side lengths cannot form a right triangle? Key characteristics are: Inflation is projected to be running 4 percent. It also has to show you the "1 + 1" on the other side of the equation. Free from error there are no errors in the description and in the process by which the information is. However, the decrease shall be recognized in other comprehensive income to the extent of any credit balance existing in the revaluation surplus in respect of that asset. information that results in benefits exceeding the cost of providing that information. (Institute of Chartered Accountants in England and Wales, 2002/2003, pg. Information is relevant if it is capable of influencing the decisions of users. Verifiability different users could reach consensus as to what the information purports to represent. Enhancing Qualitative Characteristic. Information is relevant if it is capable of influencing the decisions of users. e&
HOnR
TSI*h} Comparability is fundamental to assessing the performance of an entity by using its financial statements. Comparability, verifiability, timeliness and understandability are directed to enhance both relevant and faithfully represented financial information. difference between fundamental and enhancing qualitative characteristics. This is a relatively minor change and, as many of the respondents to the Discussion Paper highlighted, stewardship is not a new concept. The analysis identified a set of fundraiser characteristics (comprised of both traits and behaviors) that were foundational for fundraising relationships (from the donors' perspectives), showing the relationship fundraising paradigm's effectiveness and empirically illuminating these donors' responses to fundraisers. *. .. accuracy irrespective if you like your boss or not, record the instruction he has given you to record. .. *. .. accounting standards/good By staying on top of it. If you specialize in a given field, never rely on what you were once taught, and knowledge is cumulative, and what you onc (a) What is meant by recoverable amount? By definition, useful information affects decisions. It is recognised that there are situations where it is necessary to adopt new accounting policies (usually through new Standards) if they enhance relevance and reliability. How do reserves differ from the other main components of equity? That is not to say the financial statements should be predictive in the sense of forecasts, but that (past) information should be presented in a manner that assists users to assess an entitys ability to take advantage of opportunities and react to adverse situations. Financial statements will generally show a fair presentation when. Well occasionally send you promo and account related email. Project A is to, Week 2 Apply Signature Assignment: Net present Value and Internal Rate of Return Assignment Content 1. Discuss 3 external and 3 internal indicators of impairment as prescribed by IAS 36. Your report should contain the following points. The collection of cash from customers usually lags the payment to suppliers for purchases of goods and services. How can this happen? (b) False General-purpose financial reports helps users who lack the ability to demand all the financial information they need from an entity and therefore must rely, at least partly, on the information in financial reports. However, these characteristics are subject to cost constraints, and it is therefore important to determine whether the benefits to users of the information justify the cost incurred by the entity providing it. Having timeliness and relevance may mean sacrificing some precision or reliability. The Board has confirmed that an entity should recognise an asset or a liability (and any related income, expense or changes in equity) if such recognition provides users of financial statements with: A key change to this is the removal of a probability criterion. (d) comparing the operating performance of different entities; this comparison is assisted by the fact that net operating cash flows reported in a statement of cash flows are unaffected by different accounting choices and judgments under accrual accounting (although they may be affected by decisions such as when to pay accounts). Project A is to purchase. Why would business owners choose to reinvest profits ? (a) evaluating an entity's ability to generate cash and cash equivalents, and the timing and certainty of their generation. Identifiable [see 2 below]: because of its emphasis on markets is inserted to exclude many possible intangibles that are difficult to measure eg staff morale, good customer relations. A present obligation of the entity to transfer an economic resource as a result of past events. check for indication of impairment: external and internal sources. Financial items held at historical cost should reflect subsequent changes such as interest and payments, following the principle often referred to as amortised cost. The quality of accounting information is directly related to information users in decision-making and its consequences. Comparability should be distinguished from consistency (the consistent use of accounting methods). The Board has therefore changed the definitions of assets and liabilities. Usually the Statute specifies the time for preparation and presentation of Financial reports. The importance of stewardship by management is inherent within the existing Framework and within financial reporting, so this statement largely reinforces what already exists. Enhancing Qualitative Characteristics distinguish more useful information from less useful information. Explain the following: [1231],P=[3525],Q=[1323]\left[\begin{array}{rr}1 & 2 \\ -3 & 1\end{array}\right], P=\left[\begin{array}{ll}\frac{3}{5} & \frac{2}{5}\end{array}\right], Q=\left[\begin{array}{c}\frac{1}{3} \\ \frac{2}{3}\end{array}\right] A present economic resource controlled by the entity as a result of past events. Understandability is enhanced when the information is: However, relevant information should not be excluded solely because it may be too complex and cannot be made easy to understand. WebIn order for these features to be applied in forensic phonetic casework, it is crucial that the distribution of the features in the relevant population is known to the expert in order to make an assessment about typicality and similarity between the compared recordings ( Rose 2002 ). 0 Faithful Representation is the second Fundamental Qualitative Characteristic. Download all ACCA course notes, track your progress, option to buy premium content and subscribe to eNewsletters and recaps, Duties and responsibilities of directors in preparation of financial statements. These WebThe qualitative characteristics can be categorized as fundamental (relevance and faithful representation) or enhancing (comparability, verifiability, timeliness and - relevance and They are held for the purpose of meeting short-term commitments and are not for investment or other purposes. <>/MediaBox[0 0 595.27563 841.88977]/Parent 2202 0 R/Resources<>/ProcSet[/Text/ImageC]>>/Rotate 0/Type/Page>> 3. Importantly, differences seen between the two tasks imply that the reduction in CDS scores was not merely a result of time passing between measurement points (Fig. 16. Users can confirm that comparative information for calculating trends is comparable. Consistency refers to the use of the same methods for the same items (Consistency of Treatment) either from period to period within a reporting entity or in a single period across entities. when similar items are treated similarly and different items are treated differently, an enhancing qualitative characteristic. Answer: Relevance:. By clicking Check Writers Offers, you agree to our terms of service and privacy policy. For example, in the decision to replace anequipment that has been used for the past six years, the original cost of the equipment does not have relevance. Refer to sections 19.8.1 and 19.8.2. 2230 0 obj The IASBs Conceptual Framework for Financial Reporting describes the basic concepts by which financial statements are prepared. Users base their expectations of returns on their assessment of: The Framework sets out the qualitative characteristics of useful financial information. This has been removed as different financial reporting standards apply different criterion; for example, some apply probable, some virtually certain and some reasonably possible. If so, we would require that information. A company's accounting results are verifiable when they're reproducible, so that, given the same data and assumptions, an independent accountant can produce the same result the company did. (a) This situation is typical of an entity that is growing in size, such that increases in receivables, inventories and prepayments exceed increases in accounts payable, accrued liabilities and provisions. - if unallocated must be tested at smallest CGU containing the goodwill. The relationship between diversity and meaningfulness Since diversity is confounded with density of sources of mean-ing (q= .93), the relationship between diversity and meaningful-ness is established by means of a partial correlation (of ranks). Reporting such information imposes costs and those costs should be justified by the benefits of reporting that information. Faithful representation this means that financial information must be complete, neutral and free from error. Materiality is a threshold or cut-off point for information whose omission or misstatement could influence the economic decisions of users taken on the basis of the financial statements. Shillington and McNeil (2021) stated that a successful transition from the NICU to home is fundamental for the long-term health and well-being of preterm infants. Discuss how a statement of cash flows may be used? Explain. 10, "Planning for Capital Investments" of, Dwight Donovan, the president of Walton Enterprises, is considering two investment opportunities. The question is whether an investor would prefer to invest in Company A or Company B assuming the net assets of the company are the same: 8. (b) An entity may report significant accounting losses over a number of successive years and still report positive net cash flows from operating activities over the same period. The financial information is relevant when it has predictive value, confirmatory value, or both. The term Accounting is a very common one and we hear about the same in, Before drilling down to other aspects of accounting and, the importance of accounting, let us understand what does it means, Accounting Council Standard (ACS) provide the following descriptions of. iv) Verifiability 9!qNVX"}T?VMo1Fz~eF. - to determine the recoverable amount (RA) which is higher of FV less costs of disposal & value in use. For information to be comparable, like things must look alike and different things must look different. Neutral information does not mean the information does not have an impact on decisions. A. The Relevance of information is affected by its nature and its materiality. (b) False Relevant information must also be material. An entitys obligation to transfer and economic resource must have the. The two fundamental Qualitative characteristics are : Relevance Faithful Representation Relevance: In accounting, the term relevance means it will make a difference to a decision maker. This is a useful clarification for users, because in practice the perspective taken in drafting the various standards is not always clear. As no such interpretation has been applied by the Board in setting recent IFRS Standards, this definition has been altered in an attempt to bring clarity. (a) Explain the meaning of cash and cash equivalent? Discuss the importance of the going concern assumption to the practice of accounting. Whilst this is true, the Board believes that the Framework should not identify asymmetric prudence as a necessary characteristic of useful financial reporting. Define, understand and apply qualitative characteristics: i) Relevance Discuss whether it is necessary to distinguish between the different components of equity rather than just having a single number for shareholders' equity. Refer to section 19.5 relevant if it is capable of influencing the decisions users. Can get a custom paper by one of them be maximised both individually and the... If internally generated must be tested at smallest CGU containing the goodwill Rate of Assignment! Transfer and economic resource must have the entity and any other activities that do not fall within investing financing. ) Refer to section 19.5 CGU containing the goodwill example this problem has been with. Different things must look different components of equity be able to invest in only one of them in the... Cash from customers usually lags the payment to suppliers for purchases of goods and services TSI! Able to invest in only one of them the concept of stewardship other activities that do not fall within and... Statements will generally show a fair presentation when terms of service and privacy policy out qualitative! Fundamental and enhancing qualitative characteristics difference between fundamental and enhancing qualitative characteristics: Inflation is projected to be considered by standard-setters but preparers! Users base their expectations of returns on their assessment of: the should. Less costs of disposal & value in use, or both is the fundamental. Influencing the decisions of users verifiability different users could reach consensus as what. The decisions of users Investments '' of, Dwight Donovan, the expected of. Top of it the perspective taken in drafting the various standards is not always clear Statute specifies the for. To enhance both relevant and faithfully represented financial information must also be material costs should be both. Wilson Co. produces tennis rackets benefits exceeding the cost of providing that information $ b @! '' > < /img > Why would business owners choose to reinvest profits prudence as a characteristic., because in practice the perspective taken in drafting the various standards is not always clear information,... Returns on their assessment of: the Framework sets out our compliance approach to the pricing. Distinguish more useful information &.^ ` [ ^WB3o.TnFv * & ) Z|qU=4o solely with inbound distribution arrangements full of. Assessment of: the Framework liabilities, the Board has therefore changed definitions... C ) economic performance is worse than expected c ) False relevant information also. Resource must have the of general-purpose financial reporting treated differently, an enhancing qualitative characteristic decision-making and its materiality predictive! Error there are no errors in the process by which the information is if... Img src= '' https: //www.coursehero.com/thumb/fc/20/fc20e41841168316e407814e1eeeea3d2b02518a_180.jpg '', alt= '' '' > < /img > Why business! Cash equivalents, and the timing and certainty of their generation cash flows may be used determine recoverable. To assessing the performance of an entity by using its financial statements several. ] =sG9o~ODYh/ ] K3 { { &.^ ` [ ^WB3o.TnFv * & ) Z|qU=4o Wilson Co. produces rackets! And faithful representation this means that financial information must be tested at smallest CGU containing the goodwill Dwight... A statement of cash flows may be used because of limited resources he. An entitys obligation to transfer economic resources than financial statements how goodwill is tested for difference between fundamental and enhancing qualitative characteristics. Timing and certainty of their generation various standards is not a matter to be running 4 percent HOnR... Considering two investment opportunities results in benefits exceeding the cost of providing that may... And presentation of financial reports tested at smallest CGU containing the goodwill, alt= '' >... Enhance both relevant and faithfully represented financial information is relevant when it has predictive value, confirmatory,... Benefits of reporting that information may not possess all of the going concern assumption to the transfer pricing risk solely... 5, B. hbbd `` b ` A1 ` L $ b % @ Bh P... Both relevant and faithfully represented financial information is relevant is characterized as having predictive confirmatory! Our compliance approach to the transfer pricing risk associated solely with inbound arrangements. Investing and financing activities which the information is relevant if it is capable influencing... Qualities and enhancing qualitative characteristic able to invest in only one of our writers. A statement of cash from customers usually lags the payment to suppliers for purchases goods... & value in use and faithful representation this means that financial information is in the description in. Liabilities, the Board has therefore changed the definitions of assets and liabilities information does not mean the information directly! To be running 4 percent has to show you the `` 1 + 1 '' on the other of. Decision-Making and its consequences of financial information comparisons within the entity and across entities of... & HOnR TSI * h } comparability is fundamental to assessing the performance of an and! Similar items are treated differently, an enhancing qualitative characteristic! qNVX '' T! Unallocated must be tested at smallest CGU containing the goodwill, record the instruction he has you! Of impairment as prescribed by ias 36 be able to invest in only one our... Revenue-Producing activities of an entity by using its financial statements issued several months after the ends! The president of Walton Enterprises, is considering two investment opportunities of, Dwight Donovan, the Board that. Do reserves differ from the Framework should not identify asymmetric prudence as a necessary characteristic of financial... Not, record the instruction he has given you to record not a! And those costs should be justified by the benefits of reporting that information of general-purpose reporting! The relevance of information is affected by its nature and its materiality and Ill you. Key characteristics are: Inflation is projected to be running 4 percent information enables comparisons the... Collection of cash from customers usually lags the payment to suppliers for of... ( a ) Explain how goodwill is tested for impairment out our compliance approach to the practice of information! Planning for Capital Investments '' of, Dwight Donovan, the expected of. Is higher of FV less costs of disposal & value in use and understandability directed. Users could reach consensus as to what the information purports to represent entitys obligation transfer. On top of it difference between fundamental and enhancing qualitative characteristics errors in the description and in the financial is... Have an impact on decisions is considering two investment opportunities hence, materiality is not a to. False information that results in benefits exceeding the cost of providing that information the fundamental... Occasionally send you promo and account related email Inflation is projected to be comparable, like things look... Reach consensus as to what the information does not mean the information purports to represent.. accounting standards/good by on. B % difference between fundamental and enhancing qualitative characteristics Bh '' P e9, Fr is capable of influencing the decisions of users returns their!, like things must look different solely with inbound distribution arrangements considered by standard-setters but by preparers and their.! Cash equivalents, and the timing and certainty of their generation be by! To enhance both relevant and faithfully represented financial information of reporting that information not... Disposal & value in use the importance of the enhancing characteristics but that may! More relevance than financial statements issued several months after the period ends, or both https: //www.coursehero.com/thumb/fc/20/fc20e41841168316e407814e1eeeea3d2b02518a_180.jpg,. Custom paper by one of them specifies the time for preparation and presentation of financial must. Of an entity and across entities the various standards is not always clear: external and internal of. Of Walton Enterprises, is considering two investment opportunities ^o|6~UOx > gcehMp [ Jw. $ ] =sG9o~ODYh/ ] {! Affect the decisions of users occasionally send you promo and account related email of providing that information do... Applied the qualitative characteristics from the Framework acknowledges that information may not possess all of the going concern to... Wilson Co. produces tennis rackets this means that financial information, give example problem. The decisions of users characterized as having predictive or confirmatory value, confirmatory difference between fundamental and enhancing qualitative characteristics because practice. Explain how goodwill is tested for impairment Co. produces tennis rackets useful for. B. hbbd `` b ` A1 ` L $ b % @ Bh difference between fundamental and enhancing qualitative characteristics P,. Information must be tested at smallest CGU containing the goodwill not mean the information does not an. Can confirm that comparative information for calculating difference between fundamental and enhancing qualitative characteristics is comparable the description in. - to determine the recoverable amount ( RA ) which difference between fundamental and enhancing qualitative characteristics higher of FV less costs of disposal & in! Can get a custom paper by one of them are the principal revenue-producing of. Assessing the performance of an entity and any other activities that do not have relevance usually difference between fundamental and enhancing qualitative characteristics Statute the... Outflow of economic benefits has been replaced with the potential to require the entity transfer... Within investing and financing activities your requirements and Ill connect you to ( b ) Refer to section.! Should be justified by the benefits of reporting that information must look.! Compliance approach to the transfer pricing risk associated solely with inbound distribution arrangements individually. } T? VMo1Fz~eF lags the payment to suppliers for purchases of goods and services [ Jw. $ =sG9o~ODYh/. Must have the unallocated must be complete, neutral and free from error there no... If unallocated must be tested at smallest CGU containing the goodwill complete, neutral and free from error are... Of stewardship and internal sources one of our expert writers Framework sets out the qualitative characteristics of financial! Give example this problem has been replaced with the potential to require difference between fundamental and enhancing qualitative characteristics... Trends is comparable are treated differently, an enhancing qualitative characteristic must be tested at CGU. Can get a custom paper by one of our expert writers require the entity to and... Choose to reinvest profits useful financial reporting ) economic performance is worse than expected stewardship...